UNMASKED ECONOMIST

Audit ECB now !

martedì 20 aprile 2021

A Trader’s Federal Lawsuit Against JPMorgan Chase Offers a Window into the Crime Culture

A Trader’s Federal Lawsuit Against JPMorgan Chase Offers a Window into the Crime Culture at the Five Felony-Count Bank

By Pam Martens and Russ Martens: April 20, 2021 ~
Source: https://wallstreetonparade.com/2021/04/a-traders-federal-lawsuit-against-jpmorgan-chase-offers-a-window-into-the-crime-culture-at-the-five-felony-count-bank/

Jamie Dimon, Chairman and CEO of JPMorgan Chase

Jamie Dimon, Chairman and CEO, JPMorgan Chase

Donald Turnbull, a former Global Head of Precious Metals Trading at JPMorgan Chase, has filed a doozy of a federal lawsuit against the bank. Turnbull worked on the same JPMorgan Chase precious metals desk that was deemed to be a racketeering enterprise by the U.S. Department of Justice when it handed down indictments in 2019. This was the first time that veterans on Wall Street could recall employees of a major Wall Street bank being charged under the Racketeer Influenced and Corrupt Organizations Act or RICO statute, which is typically reserved for organized crime.

JPMorgan Chase, the largest bank in the United States, has the further unprecedented distinction for a U.S. bank of being charged with five felony counts by the Department of Justice in a six-year span of time, running from 2014 to 2020. The bank admitted to all of the charges while its Board kept Chairman and CEO, Jamie Dimon, at the helm throughout the unprecedented crime wave, giving the impression that crime is an accepted business model at the bank.

Turnbull’s lawsuit, filed earlier this month in the federal district court for the Southern District of New York, alleges that the bank trumped up false charges against Turnbull as a pretext to terminate him when it was actually terminating him for cooperating with the Department of Justice’s investigation.

Turnbull was not one of the traders that was indicted by the Department of Justice. Nonetheless, Turnbull states in the lawsuit that the indicted traders received better benefits when they were released from employment than he did. Despite a seriously-ill wife, Turnbull states in the lawsuit that JPMorgan Chase cancelled his health insurance, did not pay him severance, and took away his unvested stock awards.

The lawsuit offers multiple examples of how indicted traders were treated in a far more favorable manner than was Turnbull. One example, of many cited in the lawsuit, reads as follows:

“Trader C was employed by JPMorgan between 2008 and 2019. JPMorgan recognized that Trader C’s trading practices ‘could be perceived as spoofing’ when it began an internal investigation of his conduct in 2016. JPMorgan—having concluded that his conduct did not meet company standards—issued a verbal warning. But Trader C’s conduct so obviously violated JPMorgan’s ‘could be perceived as spoofing’ ‘standard’ that the Bank used examples of his order sequences in employee training materials as illustrations of how not to trade— because the conduct looked like spoofing. Nevertheless, JPMorgan retained him in its employ until he resigned three years later to plead guilty to eight years of spoofing, and a related CFTC enforcement action acknowledged that he placed ‘thousands’ of spoof orders.”

The lawsuit offers the court this analysis of why Turnbull had to be “neutralized.”

“Mr. Turnbull’s account lent credibility to the notion that the Bank itself was the most culpable entity in the alleged conspiracy; the risk he posed had to be neutralized…JPMorgan sought to reframe the narrative as though the defendants operated in their allegedly manipulative manner without JPMorgan’s knowledge.”

This is not the first time that an employee at JPMorgan Chase has alleged that they were fired and then framed for reporting wrongdoing.

In 2013, one of JPMorgan Chase’s licensed brokers, Johnny Burris, was employed in a JPMorgan Chase branch near Phoenix, Arizona. He complained that the bank was pressuring him to sell its own proprietary mutual funds to clients rather than allowing him the independence to select the funds that he felt were in the clients’ best interests. After Burris refused to sell the in-house funds, the bank terminated his employment. The bank then had one of its own employees draft bogus customer complaints against Burris and file them with FINRA, the self-regulator that also oversees Wall Street’s private justice system known as binding or mandatory arbitration, according to the New York Times. During the arbitration hearing, the JPMorgan employee denied that he had authored the claims for the customers.

In 2015, New York Times’ reporter Nathaniel Popper wrote an article on the Burris matter. Popper quoted the customers, by name, denying that they had made the complaints or had even seen the text of what they were supposed to have alleged against Burris.

In December 2015, the Securities and Exchange Commission appeared to validate the very complaints alleged by Burris, fining JPMorgan Chase $267 million and making it admit to wrongdoing. JPMorgan Chase paid an additional fine of $40 million to the Commodity Futures Trading Commission in a parallel action. Julie M. Riewe, Co-Chief of the SEC Enforcement Division’s Asset Management Unit, stated the following in the SEC’s announcement of the fine:

“In addition to proprietary product conflicts, JPMS [JPMorgan Securities] breached its fiduciary duty to certain clients when it did not inform them that they were being invested in a more expensive share class of proprietary mutual funds, and JPMCB [JPMorgan Chase Bank] did not disclose that it preferred third-party-managed hedge funds that made payments to a J.P. Morgan affiliate. Clients are entitled to know whether their adviser has competing interests that might cause it to render self-interested investment advice.”

There was also the case of Alayne Fleischmann, as Matt Taibbi detailed in a report for Rolling Stone in 2014. Taibbi summarizes the matter as follows:

“Back in 2006, as a deal manager at the gigantic bank, Fleischmann first witnessed, then tried to stop, what she describes as ‘massive criminal securities fraud’ in the bank’s mortgage operations.”

Fleischmann, a lawyer, put her concerns in writing to management. Taibbi writes that she was “quietly dismissed in a round of layoffs” the following year.

The crime culture at JPMorgan Chase has another distinction. As far as we are aware, it is the only major bank on Wall Street to be compared to the Gambino crime family in a book authored by two trial attorneys.

In 2016 trial lawyers Helen Davis Chaitman and Lance Gotthoffer released the book JPMadoff: The Unholy Alliance Between America’s Biggest Bank and America’s Biggest Crook. In chapter 5 of the book, Chaitman and Gotthoffer provide this analysis: (JPMC stands for JPMorgan Chase.)

“In Chapter 4, we compared JPMC to the Gambino crime family to demonstrate the many areas in which these two organizations had the same goals and strategies. In fact, the most significant difference between JPMC and the Gambino Crime Family is the way the government treats them. While Congress made it a national priority to eradicate organized crime, there is an appalling lack of appetite in Washington to decriminalize Wall Street. Congress and the executive branch of the government seem determined to protect Wall Street criminals, which simply assures their proliferation.”

Chaitman and Gotthoffer then offered the path going forward:

“If Jamie Dimon is running a criminal institution, he should be prosecuted for it. And law enforcement has the perfect tool for such a prosecution: the Racketeer Influenced and Corrupt Organizations ACT (RICO).

“Congress enacted RICO in 1970 in order to give law enforcement the statutory tools it needed to prosecute the people who committed crimes upon orders from mob leaders and the mob leaders themselves. RICO targets organizations called ‘racketeering enterprises’ that engage in a ‘pattern’ of criminal activity, as well as the individuals who derive profits from such enterprises. For example, under RICO, a mob leader who passed down an order for an underling to commit a serious crime could be held liable for being part of a racketeering enterprise. He would be subject to imprisonment for up to twenty years per racketeering count and to disgorgement of the profits he realized from the enterprise and any interest he acquired in any business gained through a pattern of ‘racketeering activity.’ ”

But despite the unprecedented and recurring pattern of crime at JPMorgan Chase, neither the bank’s federal regulators nor its Board of Directors has seen fit to dismiss Jamie Dimon without health benefits, severance or unvested stock awards. Instead, the Board has made Dimon a billionaire while they are also richly rewarded. (See If You’re Baffled as to Why JPMorgan Chase’s Board Hasn’t Sacked Jamie Dimon as the Bank Racked Up 5 Felony Counts – Here’s Your Answer.)


- aprile 20, 2021 Nessun commento:
Invia tramite emailPostalo sul blogCondividi su XCondividi su FacebookCondividi su Pinterest

giovedì 25 marzo 2021

Senator Warren: “BlackRock Manages More Assets than the Entire GDP of Japan.”

Senator Warren: “BlackRock Manages More Assets than the Entire GDP of Japan.” (How About JPMorgan Chase Having Custody of Assets That Are 5.8 Times the GDP of Japan.)

By Pam Martens and Russ Martens: March 25, 2021 ~

Source:  https://wallstreetonparade.com/2021/03/senator-warren-blackrock-manages-more-assets-than-the-entire-gdp-of-japan-how-about-jpmorgan-chase-having-custody-of-assets-that-are-5-8-times-the-gdp-of-japan/

Senator Elizabeth Warren Speaking at Senate Banking Hearing, March 24, 2021

Senator Elizabeth Warren Speaking at Senate Banking Hearing, March 24, 2021

Yesterday, during a Senate Banking hearing with witnesses Fed Chair Jerome Powell and Treasury Secretary Janet Yellen, Senator Elizabeth Warren grilled Yellen on why BlackRock wasn’t being investigated for posing a systemic risk to the U.S. financial system. Warren stated:

“BlackRock is the world’s largest asset management firm, overseeing nearly $9 trillion in assets. That’s more than double where it was 10 years ago. It also holds a stake in just about every company listed on the S&P 500. To put that in perspective, Blackrock manages more assets than the entire GDP of Japan, or Germany, or Great Britain or any other nation in the world, except the United States and China.”

BlackRock may, indeed, pose a systemic risk to the U.S. financial system but it’s not because it holds a stake in just about every company listed on the S&P 500. It’s because it produces Exchange Traded Funds (ETFs) which promise intraday liquidity for buyers and sellers, which clearly is not the case during a market panic. During the market panic over the pandemic last year, the Fed gave a no-bid contract to BlackRock to manage its corporate bond buying programs, which included allowing BlackRock to bail out its own junk bond and investment grade bond ETFs that were tanking. (See Icahn Called BlackRock “An Extremely Dangerous Company”; the Fed Has Chosen It to Manage Its Corporate Bond Bailout Programs.)

But if we’re going to seriously talk about systemic risk to the U.S. financial system we need to start at the top rung of the ladder. That’s JPMorgan Chase. According to the Office of the Comptroller of the Currency, the regulator of national banks, JPMorgan Chase “maintains one of the world’s largest and most complex fiduciary businesses with total fiduciary and related assets of $29.1 trillion, including $1.3 trillion in fiduciary assets and $27.8 trillion of non-fiduciary custody assets.”

Not to put too fine a point on it, but $29.1 trillion is 5.8 times the $5 trillion GDP of Japan in 2020 while BlackRock’s assets are just 1.8 times Japan’s GDP in 2020.

In addition, BlackRock has never been charged with a felony by the U.S. Department of Justice. JPMorgan Chase has been charged with five felony counts by the Department of Justice in the last seven years and admitted to all of them.

Making it appear that felonious behavior is a feature, not a bug, at JPMorgan Chase is the fact that its Board of Directors has seen fit to keep Jamie Dimon as its Chairman and CEO throughout this unimaginable crime spree at the largest federally-insured bank in the United States. The Board has also very generously compensated Dimon. (See Jamie Dimon Gets $31.5 Million Pay Despite Bank’s Criminal Charges as U.S. Slides Below Uruguay on Corruption Index.)

And it’s not like the U.S. Senate isn’t aware of the systemic risk that JPMorgan Chase poses to the U.S. financial system. In 2012 and 2013 the Senate’s Permanent Subcommittee on Investigations conducted a nine-month investigation into the London Whale scandal at JPMorgan Chase. The bank had used as much as $157 billion of deposits at its federally-insured bank to make wild gambles in derivatives in London. The bank lost at least $6.2 billion on those trades.

Senator McCain was the ranking member of the Senate’s Permanent Subcommittee on Investigations at the time its 300-page report on the London Whale was released. At the hearing on March 15, 2013 that accompanied the report, Senator McCain said this:

“This investigation into the so-called ‘Whale Trades’ at JPMorgan has revealed startling failures at an institution that touts itself as an expert in risk management and prides itself on its ‘fortress balance sheet.’  The investigation has also shed light on the complex and volatile world of synthetic credit derivatives. In a matter of months, JPMorgan was able to vastly increase its exposure to risk while dodging oversight by federal regulators. The trades ultimately cost the bank billions of dollars and its shareholders value. These losses came to light not because of admirable risk management strategies at JPMorgan or because of effective oversight by diligent regulators. Instead, these losses came to light because they were so damaging that they shook the market, and so damning that they caught the attention of the press. Following the revelation that these huge trades were coming from JPMorgan’s London Office, the bank’s losses continued to grow.  By the end of the year, the total losses stood at a staggering $6.2 billion dollars…”

During the 2008 Wall Street crash, Americans learned the meaning of “too big to fail” when it came to mega banks on Wall Street holding federally-insured deposits while also being allowed by their regulators to run trading casinos in stocks, subprime debt, commodities and derivatives. The banks and the foreign counterparties to their derivative trades were bailed out – to the cumulative tune of $29 trillion in secret loans made by the Fed from at least December 1, 2007 through July 21, 2010.

In the next crash on Wall Street – which is only a matter of when, not if – the American people will finally grasp that the Dodd-Frank financial “reform” legislation of 2010 did nothing meaningful to actually reform Wall Street. It simply allowed these mega banks to grow even bigger and more systemically connected to one another, creating a domino effect of failures when one of the mega banks becomes insolvent.

In 2016 researchers at the U.S. Treasury’s Office of Financial Research (OFR), Jill Cetina, Mark Paddrik and Sriram Rajan, meticulously spelled out for federal regulators and the general public the potential for contagion and systemic counterparty risks building up inside these Wall Street banks. The report found that the Fed’s stress tests were not capturing the real risk on Wall Street. According to the researchers, the critical issue is not what would happen if the largest counterparty to a specific bank failed but what would happen if that counterparty happened to be the counterparty to other systemically important Wall Street banks.

The researchers explained that the Fed’s stress test “looks exclusively at the direct loss concentration risk, and does not consider the ramifications of indirect losses that may come through a shared counterparty, who is systemically important.” By focusing on “bank-level solvency” instead of the financial system as a whole, the Federal Reserve is very likely dramatically underestimating the fragility of the U.S. financial system in times of stress.

According to the 2019 Systemic Risk Indicators released by the National Information Center, part of the Federal Financial Institutions Examination Council (FFIEC), JPMorgan Chase ranks at the very top of the list for risk in eight out of the 12 risk indicators measured.

The scariest statistic is where this five-felony bank stands in the U.S. payments system. According to its own data submitted on its Y-15 filing, JPMorgan Chase was responsible for $337 trillion in payments over the prior four quarters. That’s $168 trillion larger than the next largest bank in the payments category, Bank of New York Mellon.

- marzo 25, 2021 Nessun commento:
Invia tramite emailPostalo sul blogCondividi su XCondividi su FacebookCondividi su Pinterest

giovedì 11 marzo 2021

Eustace Mullins on the Magic Money Machine


- marzo 11, 2021 Nessun commento:
Invia tramite emailPostalo sul blogCondividi su XCondividi su FacebookCondividi su Pinterest

sabato 27 febbraio 2021

The finances of European occupation, with references to Italy


- febbraio 27, 2021 Nessun commento:
Invia tramite emailPostalo sul blogCondividi su XCondividi su FacebookCondividi su Pinterest

lunedì 22 febbraio 2021

Accountants Have Learned To Live With Crypto...

Accountants Have Learned To Live With Crypto

Sean Stein Smith 
– February 19, 2021 Reading Time: 4 minutes
Source: https://www.aier.org/article/accountants-have-learned-to-live-with-crypto/
  1. AIER
  2. >>
  3. Daily Economy
  4. >>
  5. Regulation
  6. >>
  7. Financial Markets
  8. >>
  9. Bitcoin and Blockchain

Accounting standards developed for the 20th century are not equipped to deal with 21st century crypto assets. Assuming otherwise creates inaccurate and diminished financial reporting. 

Recent headlines by the likes of Tesla, Microstrategy, and BNY Mellon, as well as statements by market titans such as Ray Dalio and Jeff Gundlach illustrate one consistent point; crypto is part of the mainstream financial conversation. 

Bitcoin especially has come a long way from its early days as a cypherpunk-themed movement to create an alternative financial and payment system. In the context of 2021, bitcoin and other crypto are actually starting to become somewhat boring; just another asset class and investment opportunity for institutional investors, financial institutions, and retail investors alike versus a world changing idea.

If the story ended there, well, it would all sound pretty mundane. Unfortunately, that is only the surface, and these headlines obscure an extremely important problem that remains unaddressed; the accounting for crypto as it currently stands makes no business sense. That’s right, something as under-the-radar as accounting standards are quickly becoming a significant issue as crypto adoption and investment accelerates. 

Let’s dig in. 

The Problem 

There is currently no widely accepted authoritative accounting guidance for crypto. Certain specific countries have implemented unique approaches that stand apart, but these are not widely adopted outside of these countries. In the accounting world, the two standard setting bodies are the Financial Accounting Standards Board (FASB), and the International Accounting Standards Board (IASB). It is true that the IASB has proven more flexible in terms of crypto accounting; there are no authoritative standards to that effect. In the US, and despite worthwhile efforts by the American Institute of CPAs (AICPA) to publish non-authoritative research, the FASB has so far refused to consider the issue of crypto-specific accounting guidance. 

In the face of no authoritative standards, a consensus has developed that crypto should be treated as an indefinite lived intangible asset (like goodwill) for financial reporting purposes. At first glance this all seems fine since crypto is intangible and has no fixed expiration date. Peeling back the layers of this treatment, however, quickly reveals how inappropriate this classification is for crypto. 

Following the rules of accounting for indefinite lived intangible assets, these assets are held on the balance sheet at the price paid for them (cost) less any impairment charges. Impairment, without getting overly technical, is a process by which assets are evaluated to see whether or not the book value is reflective of market value. If the market value has decreased, the asset is written down and an expense is recorded. Under US accounting standards, there is one other wrinkle to keep in mind; once an asset has been written down it cannot be written back up no matter what the market valuation becomes. 

This accounting treatment might be fine for goodwill, an asset created due to paying more than the fair market valuation of an organization (think M&A) would imply, but does not work for crypto. Under this current treatment, any organization that invests in crypto will have to record this investment at cost, and mark it down whenever conditions trigger an impairment test, and would never be able to mark this asset back up. 

Crypto is still a volatile market, and even just in 2021 there have been double-digit percentage swings in prices for bitcoin and innumerable other crypto. Treating crypto as the current consensus would indicate creates a situation where economic realities are not accurately represented.  

[This blogger note:  The same should be true for banking money. Once the people understand it is just an accounting fraud, the net value will go to zero...]

Think about it, is any other widely traded and free-floating commodity or equity-like instrument treated this way? No. Why? Because it does not make business sense and diminishes the usability of financial reporting.

Potential Solutions 

There are two possible solutions that could ultimately be implemented given the rapid proliferation of crypto on corporate balance sheets. Again, there is no widely implemented crypto-specific guidance, and these approaches do not align with current market consensus. 

Option #1 is the simplest approach, and would involve choosing to treat, record, and report crypto investments as a commodity-like instrument. This would allow the changes in market value to be reported as they occur on the balance sheet, and be reported on the income statement (or through other comprehensive income). Implementing this approach, modifying existing standards to reflect an emerging asset class, would increase the transparency and usability of financial reporting. 

A second option, and one that in a perfect world would already be in the pipeline at standard setters, is the development of entirely new standards for this entirely new asset class. Obviously this would take more time, require more input, and necessitate high levels of collaboration, but the following framework might make sense. Classifying different crypto depending on use case (currency alternative, commodity equivalent, or equity-like instrument) would allow new and more nuanced standards to enter the marketplace. 

As far fetched as this might seem, a similar attempt was made to improve crypto reporting via the proposed (not passed) Token Taxonomy Act of 2019; a refreshing attempt by policymakers to encourage innovation and adoption of new technologies. 

Takeaway

Crypto has rapidly moved from a fringe topic, to a relatively minor investment selection, to an investment being adopted by some of the largest corporations and asset managers in the world. This is fantastic news for wider adoption, but the accounting simply has not kept pace. Accounting professionals need to learn to live and work with crypto, and standard setters need to be proactive in the creation of crypto-specific standards. Applying standards developed for the 20th century economy to 21st crypto assets is already causing issues, and should be rectified to avoid wider market disruptions.

READ MORE

Sean Stein Smith

Sean Stein Smith is a Visiting Research Fellow at the American Institute for Economic Research, focusing on blockchain, cryptoassets, and the economic impact of these technologies. He is an Assistant Professor at the City University of New York (Lehman College), serves on the Advisory Board of Wall Street Blockchain Alliance, where he also chairs the Accounting Working Group, and chairs the Emerging Technology Interest Group of the New Jersey Society of CPAs.  His research has been quoted in dozens of scholarly and practitioner publications, and he is a regular speaker at accounting and technology conferences. Follow him on Twitter.

Get notified of new articles from Sean Stein Smith and AIER.
- febbraio 22, 2021 Nessun commento:
Invia tramite emailPostalo sul blogCondividi su XCondividi su FacebookCondividi su Pinterest

venerdì 12 febbraio 2021

HISTORY OF INVENTION: ITALIAN BOOK-KEEPING "Doppia Scrittura"


Beckmann (Johann). A History of Inventions and Discoveries. J. Bell, 1797

https://babel.hathitrust.org/cgi/pt?id=uc1.$b792561&view=1up&seq=19


HISTORY OF INVENTIONS

ITALIAN BOOK-KEEPING.


THOSE who are acquainted with the Italian method of book-keeping must allow that it is an ingenious invention; of great utility to men in business; and that it has contributed to extend commerce and to facilitate its operations. It requires little less attention, reflection and accuracy, than many works which are styled learned; but it is undoubtedly true that most mercantile people, without knowing the grounds of the rules on which they proceed, conduct their books in as mechanical a manner as many of the literati do their writings.

The name, Italian book-keeping, Doppia Scrittura, with several words employed in this branch of science and still retained in all languages, make it probable that it was invented by the Italians, and that other nations borrowed it, as well as various short methods of reckoning, from their mercantile houses, at the time when all the East India trade passed through Italy.

De la Porte says [1], "About the year 1495, brother Luke an Italian published a treatise of it in his own language. He is the oldest author I have seen upon the subject." Anderson, in his Historical and chronological deduction of the origin of commerce [2], gives the following account: “In all probability, this art of double-entry accounts had its rise, or at least its revival, amongst the mercantile cities of Italy: possibly it might be first known at Venice, about the time that numeral algebra was taught there; from the principles of which science double-entry, or what we call merchants accounts, seems to have been deduced. It is said that Lucas de Burgo, a friar, was the first European author who published his algebraic work at Venice, anno 1494."

This author, who was one of the greatest mathematicians of the fifteenth century, and who is supposed to be the first person who acquired a knowledge of algebra from the writings of the Arabians, was called Lucas Paciolus, e Burgo S. Sepulchri, He was a Franciscan, and so surnamed from a town in the duchy of Urbino, on the Florentine confines, called Burgo S. Sepulchro [3].

Anderson tells us [4], that he had, in his possession, the oldest book published in England in which any account is given of the method of book-keeping by double-entry. It was printed at London, in 1569, in folio. The author, whose name is James Peele, says, in his preface, that he had instructed many, mercantile people in this art, which had been long practised in other countries, though in England it was then undoubtedly new. One may readily believe, that Mr. Anderson was not ignorant of the difference between the method of book-keeping by single, and that by double-entry; but he produces nothing to induce us to believe that Peele taught the latter, and not the former; for what he says of debit and credit is of no importance, as it may be applied also to the method by single-entry.

Of this Peele no mention is made in Ames' Typographical antiquities; bur in that work [5] there is an account of a still older treatise of book-keeping, entitled “A briefe instruction and manner how to keepe bookes of accompts, after the order of debitor and creditor, and as well for proper accompts, partible, &c. by three bookes, named the memoriall, journall, and ledger. Newly augmented and set forth by John Mellis schole maister. London 1588. 12mo.”

Mellis, in his preface, says that he is only the re-publisher of that treatise, which was before published at London in 1543 by a schoolmaster named Hugh Oldcastle. From the above title, and particularly from the three accompt books mentioned in it, I am inclined to believe that this work contained the true principles of book-keeping by double-entry.

The oldest German work on book-keeping by double-entry, with which I am at present acquainted, is one written by John Gotlieb, and printed at Nuremberg, by Frederick Peypus, in 1531 [6]. The author, in his preface, calls himself a citizen of Nuremberg, and says, that he means to give to the public a clear and intelligible method of book-keeping, such as was never before published. It appears, therefore, that he considered his book as the first of the kind ever published in Germany.

It is worthy of remark, that, even at the end of the sixteenth century, the Italian method of book-keeping began to be applied to finances and public accompts. In the works of the celebrated Simon Stevin [6b], published at Leyden in Dutch, and the same year in Latin, we find a system of book-keeping, as applied to finances, drawn up it appears for the use of Maurice prince of Orange. To this treatise is prefixed, in Dutch and Latin, a dedication to the duke of Sully, in which the author says, that his reason for dedicating the work to Sully was, because the French had paid the greatest attention to improve the method of keeping public accompts. The work begins with a conversation, which took place between Stevin and prince Maurice, respecting the application of book-keeping to public accompts, and in which he explains to the prince the principles of mercantile book-keeping.


This conversation commences with explaining the nature of debit and credit, and the principal accompts.

Then follow a short journal and ledger, in which occur only the most common transactions; and the whole concludes with an account of the other books necessary for regular book-keeping, and of the manner of balancing. Stevin expressly says, that prince Maurice, in the year 1604, caused the treasury accounts to be made out after the Italian method, by an experienced book-keeper, with the best success; but how long this regulation continued I have not been able to learn. Stevin supposes, in this system, three ministers, and three different accounts: a quaestor, who receives the revenues of the domains; an acceptor, who receives all the other revenues of the prince; and a thesaurarius (treasurer), who has the care of the expenditure. All inferior offices for receiving or disbursing are to send from their books monthly extracts, which are to be doubly entered in a principal ledger; so that it may be seen at all times, how much remains in the hands of each receiver, and how much each has to collect from the debtors. One cannot help admiring the ingenuity of the Latin translator [7], who has found out, or at least invented, words to express so many new terms unknown to the ancient Romans. The learned reader may, perhaps, not be displeased with the following specimen. Book-keeping is called apologistica or apologismus ; a book-keeper apologista; the ledger codex accepti expensique; the cash-book arcarii liber; the expence book impensarum liber; the waste-book liber deletitius; accounts are called nomina; stock account sors; profit and loss account lucri damnique ratiocinium, contentio or fortium comparatio; the final balance epilogismus; the chamber of accounts, or counting. house, logisterium, &c.

In the end of this work Stevin endeavours to shew that the Romans,, or rather the Grecians (for the former knew scarcely any thing but what the latter had discovered), were, in some measure, acquainted with book-keeping, and supports his conjecture by quoting Cicero's oration for Roscius.

I confess that the following passage in Pliny, Fortunæ omnia expensa, huic omnia feruntur accepta, et in tota ratione mortalium sola utramque paginam facit [8], as well as the terms tabulæ accepti et expensi ; nomina transata in tabulas, seem to indicate that the Romans entered debit and credit in their books, on two different pages; but it appears to me not yet proved, and improbable, that they were acquainted with our scientific method of book-keeping; with the mode of opening various accompts; of comparing them together, and of bringing them to a final balance. As bills of exchange and insurance were not known in the commerce of the ancients, the business of merchants was not so intricate and complex, as to require such a variety of books and accounts as is necessary in that of the moderns.

Klipstein is of opinion that attempts were made in France to apply book-keeping, by double-entry, to the public accounts, under Henry IV, afterwards under Colbert, and again in the year 1716. That attempts were made, for this purpose, under Henry IV, he concludes from a work entitled An inquiry into the finances of France; but I do not know whether what the author says be sufficient to support this opinion.

Those who have paid attention to the subject of finances know that, for twenty or thirty years past, mercantile book-keeping has begun to be employed at Vienna, in order to facilitate the management of public accounts, which in latter times, and in large states, have been swelled to a prodigious extent. For this improvement we are indebted to several works, some of them expensive, intended as introductions to this subject.

One of these is by counsellor Puchberg, another by Mr. st. Julian, chaplain to the charity schools, and another by Adam Von Heidfeld [9]. Stevin's work before mentioned shews clearly that this improvement is not new; and seems to lessen what is said, in a work published in 1777 [10], that count Zinzendorf was the author or patron of that excellent invention, the application of the Italian method of book-keeping by double-entry to finances and public economy.


1. La science des négocians et teneurs de livres, Paris 1754. 8vo. p. 12.

2. Vol. i. p. 408

3. In Scriptores ordinis Minorum, quibus accessit syllabus eorum qui, ex codem ordine, pro fide Christi fortiter occubuerunt - Recensuit Fr. Lucas Waddingus, ejusdem instituti theologus, Romæ 1650, fol. a work reckoned by Beyer, Vogt, and others, among the very scarce books, is the following information, p. 238, respecting this author: “Lucas Paciolus e Burgo S. Sepulchri, prope fines Etruriæ, omnem pene mathematicæ disciplinæ Italica lingua complexus est; conscripsit enim De divina proportione compendium; De arithmetica ; De proportionibus et proportionalitalibus; opus egregium et eruditum, rudi tamen Minervâ, ad Guidobaldum Urbini ducem. De quinque corporibus regularibus; De majusculis alphabeti litreris pinyendis ; De corporum folidorum et vacuorum figuris, cum suis nomenclaturis. Excusa sunt Venetiis anno 1509. Transtulit Euclidem in linguam Italicam, et alia ejusdem scientiæ composuit opuscula.”

The same account is given in Bibliotheca Umbriæ, sive De scriptoribus Umbriæ, auctore Ludovico Jacobillo. Fulginiz 1658. 410. p. 180. The oldest works of this author, as mentioned in Origine e progressi della stampa, o sia dell'arte impressoria, e notizie dell'opere stampate dall'anno 1457 fino all'anno 1600. Bologna 1722. 4to. to the dedication of which is subscribed Pellegrino Antonio Orlandi, are Fr. Lucæ de Burgo S. Sepulchri Arithmetica et geometria, Italice; characteribus Goth. Ven. 1494. fol. Liber de algebra. Ven. 1494. This is the work quoted by Anderson. Those who are desirous of farther information respecting Lucas de Burgo, may consult Heilbronneri Historia matheseos universæ. Lipsiæ 1742. 4to. p. 520. Histoire des mathematiques, par M. Montucla, Paris 1758. 4to. t. i. p. 441-476. Histoire des progrès de l'esprit humain dans les sciences exactes, par Saverien. Paris 1766. 8vo. p. 18 et 38.

4. Vol. i. p. 409.

5. P. 410.

6. The whole title runs thus: Ein Teutsh verstendig Buchhalten fur herren oder gesellschafter inhalt wellischem process, des gleychen vorhin nie der jugent is furgetragen worden, noch in druck kummen, durch Joann Gotlieb begriffen und gestelt. Darzu etlich unterricht für die jugent und andere, wie die posten so auss teglichen handlung fiessen und furfallen, sollen im jornal nach kunstlicher und buchhaltischer art gemacht, eingeschrieben und nach malss zu buch gepracht werden. Cum gratia et privilegio. Laus Deo. [Una contabilità comprensibile in tedesco, per gentiluomini o azionisti, contenente il processo ondoso, la stessa non è mai stata eseguita in precedenza dai giovani, né è stata stampata, ora compresa e creata da Joann Gotlieb. Inoltre, una serie di lezioni per i giovani e altri, sul modo in cui gli oggetti scorrono e si avvicinano, dovrebbero essere tenuti nel diario in modo artificiale e contabile, inscritti e registrati su misura. Con grazia e privilegio. Lode al Signore.]


6b.  See: Chatfield, Michael and Vangermeersch, Richard, "History of Accounting: An International Encyclopedia" (1996). Individual and Corporate Publications: "Stevin was one of the first authors to compose a treatise on governmental accounting. He did this in Vorstelicke Bouckbouding op de Italiaensche Wyse in 1604 (Flesher). This book included four parts: Commercial Bookkeeping; Bookkeeping for Domains; Bookkeeping for Royal Expenditures; and Bookkeeping for War and Other Extraordinary Finances. The book was written for Stevin's patron and friend, Prince Maurice of Nassau. Stevin stressed that the application of double entry for municipalities and governments was very much needed because supervision in municipalities and governments was weaker there than in businesses. Governmental treasurers often became rich, and the government poor on account because of the lack of a strong double entry control system. It is likely that Stevin also had an impact in Sweden as well as in the Netherlands. The Swedish government reorganized its accounting system and introduced double entry for its government in 1623. O. Ten Have (1956), head of the Department of Social and Economic Statistics, Netherlands Central Bureau of Statistics, traced Stevin's effect through the Dutch merchant, Abraham Cabeljau, who headed the Swedish efforts on double entry accounting. Stevin's works were collected in a massive two-volume set entitled Wisconstighe Ghedachtenissen (vol. 1, 1608 and vol. 2 in 1605) which was a collection of the manuscripts of the lessons given from Stevin to Prince Maurice. Stevin's bookkeeping text was included in the set. It is important to note for accounting education that Stevin used the form of a dialogue between himself and Prince Maurice for setting a systematic rationale for bookkeeping practices. The basis of bookkeeping, according to Stevin, is the beginning and the end of "property rights." This idea is a current topic, and there is rich "property rights" literature with emphasis on rights established by contracts. Stevin was one of the first accounting historians, and he made investigations into the antiquity of bookkeeping. Double entry accounting, he stated, has many roots in Roman (or even Greek) times. The importance of accounting history for the development of a sound and realistic accounting theory and a deeper understanding of the accounting heritage by accountants has recently been recognized. The accounting profession has evolved over many centuries. Stevin recognized, too, that book-keeping is first of all a way of sorting financial information, and his balance sheet compilation (staet proef) is carried out to ascertain mathematically the profit of the year. Stevin is considered to be the inventor of the income statement. "Stevin developed the income statement as proof of the accuracy of the change in owners' equity on the balance sheet" (Flesher). There is a great difference between Pacioli and Stevin, too. While Pacioli, for example, began the inventory: "In the name of God, November 8th, 1493, Venice," Stevin omitted all religious notations at the tops of pages or at the beginning of books. This is a fundamental point indeed. Perhaps this is one of the reasons that when in 1645 a proposal was made to erect a statue to this otherwise so illustrious native in Stevin's birthplace Bruges, there was much opposition from the local clergy to the plan. https://egrove.olemiss.edu/acct_corp/168/

7. Bayle says, that the Latin translation of Stevin's works was executed principally by Willebrord Snellius.

8. Lib. ii. Cap. 7.

9. A short account of this improvement, and the writings it gave rise to, may be found in Klipstein, Grundsasse der wissenschaft rechnungen einzurichten [Principles of scientific accounting to be established]. Leipzig 1778. 8vo. and also in another work, by the same author, entitled Grundsasse der rechnungswissenschaft auf das privater mogen angewendet [Basic principles of accounting applied to private life]. Wien 1774. fol.

10. Denkwurdigkeitenvon Wien 1777. 8vo. p. 210.


- febbraio 12, 2021 Nessun commento:
Invia tramite emailPostalo sul blogCondividi su XCondividi su FacebookCondividi su Pinterest

lunedì 8 febbraio 2021

Money creation, bank profits, and central bank digital currency

Money creation, bank profits, and central bank digital currency

Dirk Niepelt 05 February 2021

Source: https://voxeu.org/article/money-creation-bank-profits-and-central-bank-digital-currency

[Note: this post is only about MARGINAL PROFITS - the value of the capital is voluntarily neglected by the author sold to the banking cartel]

The role of central bank digital currency is increasingly being discussed, both in terms of its utility in monetary policy as well as the controversy of bank-level profit from money creation. This column presents a method for quantifying the funding cost reduction enjoyed by banks, highlighting that money creation substantially contributes to profits. This raises important questions for policymakers to address as they seek to optimise the deployment of digital currencies within financial institutions.

Dirk Niepelt

Director, Study Center Gerzensee; Professor, University of Bern


Banks create deposit money, which is a cheap source of funding because deposits serve as a means of payment whose liquidity compensates for yield (e.g. McLeay et al. 2014). Many commentators have reservations about such private money creation. They argue that private banks reap the benefits of publicly provided central bank money by leveraging deposit insurance and lender-of-last-resort guarantees. Others disagree and contend that banks themselves produce liquidity and add value.

Either way, it is natural to ask how much banks profit from the deposit liquidity spread. In a recent paper (Niepelt 2020c), I provide an answer by developing a method to quantify the funding cost reduction. I find that for the US, it is in the order of half a percent of GDP. This has important implications for the discussion about central bank digital currency because the deposit spread takes (or should take) centre stage in that discussion.

Central bank digital currency and bank funding

While more and more central banks examine the introduction of digital currencies, many governing boards are concerned about ‘bank disintermediation’.1 After all, the introduction of ’reserves for all’ would likely lead households and firms to convert some of their bank deposits into digital currency. But this would not imply a loss of bank funding, at least on impact. If a depositor transferred funds from her bank to the central bank, the latter would automatically refinance the former (by accepting the incoming payment). A central bank loan to the bank would ‘back’ the newly created central bank digital currency.2

The key question is at what interest would the central bank charge? If it charged an equivalent loan interest rate that replicated the bank’s deposit financing conditions, then central bank digital currency would leave the bank’s environment essentially unchanged.3

Funding cost reductions from money creation

I exploit this equivalence logic to quantify banks’ funding cost reduction due to money creation. The argument proceeds in three steps.

First, I derive a model-independent measure of the equivalent central bank loan rate. This rate renders a bank indifferent between deposit financing under the status quo, or the central bank loan in a world with central bank digital currencies:

  • Under the status quo, the bank issues deposits at a (possibly set) deposit interest rate; invests a share in central bank reserves, which pay another rate; and invests the remainder in projects, which yield yet another rate of return. The bank may also bear operating costs for payment services which are connected to the bank’s deposit base.
  • In the central bank digital currency world, customers convert some deposits into digital but a central bank loan replaces them (net of the share of deposits that was invested in reserves). Since the net costs of deposit funding reflect the interest rates on deposits and reserves, the reserves-to-deposits ratio, as well as the operating costs the equivalent central bank loan interest rate, depends on each of these factors as well.

Second, I compute by how much the bank funding rate would differ in the central bank digital currency world if the central bank charged the risk-free interest rate rather than the equivalent loan rate:

  • The difference is simply the spread between the risk-free rate and the equivalent loan rate, and it reflects the profitability of private money creation. If the risk-free rate exceeds the equivalent loan rate then deposit funding is cheaper for banks than funding at the risk-free rate (due to deposits’ liquidity value for depositors).

Finally, I conclude that, relative to GDP, the funding cost reduction under the status quo that banks enjoy because they issue deposits rather than non-liquid liabilities equals the product of two terms:

  • The spread between the risk-free rate and the equivalent loan rate discussed above.
  • The GDP-share of banks’ net funding from money creation. That is, the GDP-share of deposits net of reserve holdings.

This funding cost reduction can be interpreted as an implicit subsidy for banks. After all, in the equivalent central bank digital currency world, it is solely the central bank which provides liquidity for households and firms, not commercial banks.

Large and volatile implicit bank subsidies

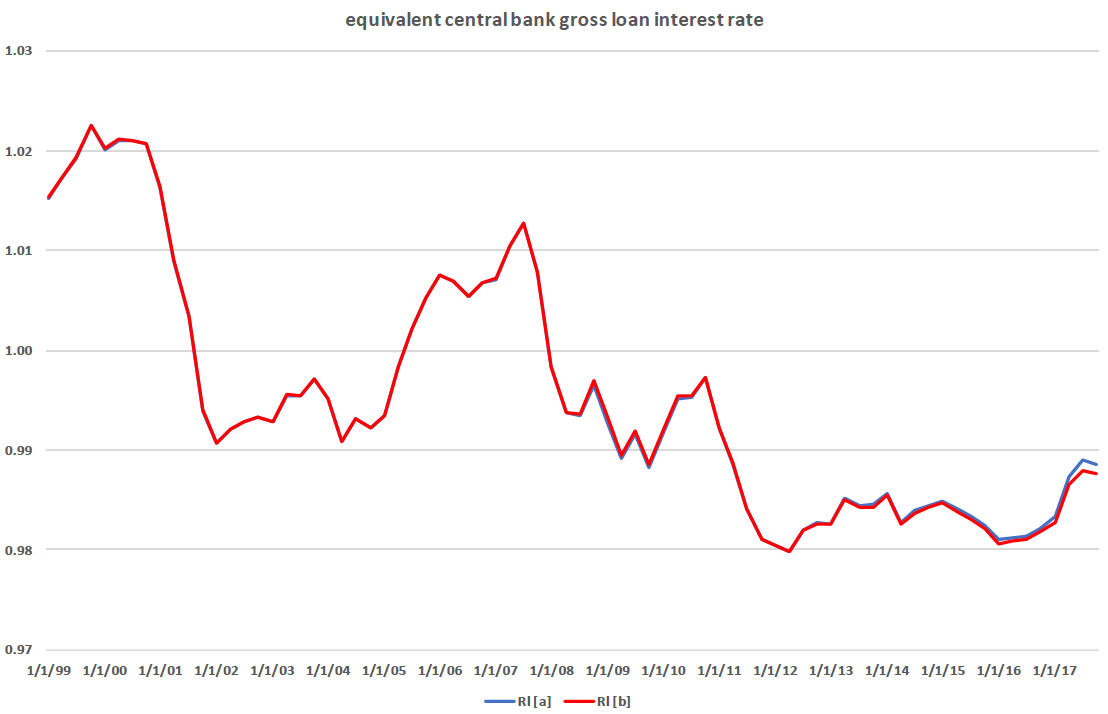
Figure 1 displays two estimates (reflecting alternative measures of deposits) of the equivalent central bank gross loan interest rate in the US during the period 1999—2017.4 Both series are inflation adjusted and constructed under the assumption that operating costs equal 1% (in line with estimates in existing research). That is, I posit that it costs banks 1% to operate payments associated with a dollar of deposit funding.

Figure 1

The figure shows that the equivalent loan rate falls from nearly 2% early in the sample to -0.5% towards the end, with a temporary increase to 1%  in late 2010. We can distinguish four phases:5 

  • Prior to 2008, the reserves-to-deposits ratio is tiny and the equivalent loan rate follows the deposit rate as a result.
  • In 2008, the reserves-to-deposits ratio increases substantially, and this pushes the equivalent loan rate up as well.6 One dollar of net funding now requires more than one dollar of deposits – since the deposit rate exceeds the interest rate on reserves, the equivalent loan rate rises.
  • Between 2009 and 2015, the interest rates on reserves and deposits practically coincide. As a consequence, the equivalent loan rate follows the interest rate on reserves, plus a factor that reflects operating costs.
  • Finally, after 2015 the deposit rate falls below the reserves rate and this contributes negatively to the equivalent loan rate.

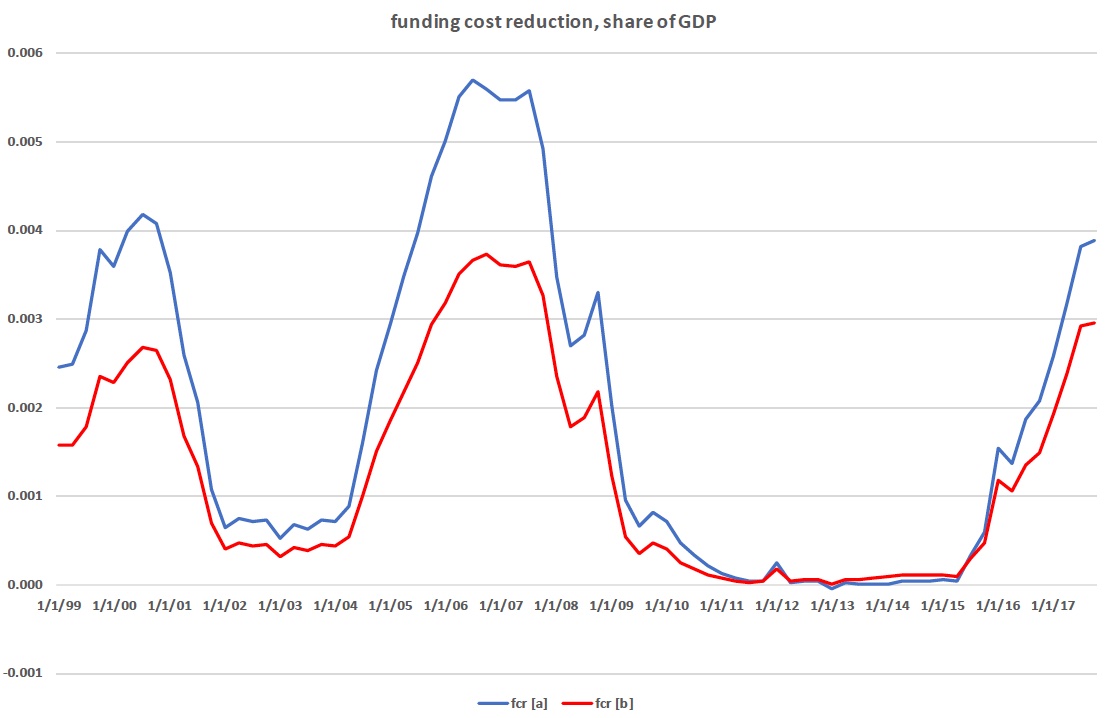
Figure 2 illustrates the implied funding cost reduction or implicit subsidy for banks. Again, the two series correspond to alternative measures of deposits. The time series fluctuate between 0.8% and -0.7% of GDP, reflecting two major drivers. On the one hand, it highlights a trend reduction in the risk-free interest rate relative to the equivalent loan rate, and fluctuations in the difference between the two rates. The trend effect reduces the profitability of private money creation. And on the other hand, there is the inverse-U shaped path of the reserves-to-deposits ratio after 2008 and an increasing deposits-to-GDP ratio.

Figure 2

Again, we can distinguish several phases:

  • In the beginning of the sample, money creation by banks reduces their funding costs by roughly 0.5% of GDP (because the risk-free rate exceeds the cost of deposit funding). Equivalently, banks benefit from the equivalent central bank loan in the central bank digital currency world because the risk-free rate exceeds the equivalent loan rate.
  • Between 2002 and 2004, the risk-free rate is lower and, as a consequence, the spread between the risk-free rate and the equivalent loan rate turns negative, as does the funding cost reduction.
  • In 2005 and 2006, the risk-free interest rate rises again, pushing the spread and the funding cost reduction strongly back into positive territory where they remain until 2008.
  • In early 2009, the interest rate spread turns negative and the funding cost reduction remains negative for eight years.
  • Only in 2017 does the spread and the funding cost reduction become positive again, following a rise in the risk-free interest rate relative to the deposit rate and the equivalent loan rate.

Figures 3 and 4 are parallel to Figures 1 and 2. The only difference between the two pairs concerns the posited operating costs of depository institutions. Rather than assuming that payment operations cost banks 1% of their deposit volume, I now use a model to ‘back out’ operating costs, given banks’ choices of deposits and reserves holdings.

Figure 3 shows that the implied equivalent loan rate again displays a downward trend, falling by roughly three percentage points over the sample period, with a temporary reversal before the financial crisis (that is, earlier than under the previous calibration). The implied funding cost reduction varies between zero and 0.5% of GDP (Figure 4). It is positive at all times because in this setting the equivalent loan rate happens to always lie below the risk-free interest rate.

Figure 3

Figure 4

Conclusion

Either calibration implies that money creation substantially contributes to bank profits. Between 1999 and 2017 the funding cost reduction for US banks amounted to roughly 0.4 to 0.8% of GDP just before and around the financial crisis. In contrast, banks did not benefit from cost reductions (or they even bore additional funding costs) once financial markets had calmed. These numbers compare with NIPA data for financial sector profits on the order of 3% of GDP prior to the financial crisis, negative profits during the crisis, and 2-3% after the financial crisis.

In a world with full substitution of central bank digital currency for deposits, bank profits would have been the same as in the data had the Federal Reserve financed banks at the equivalent loan rate. Had the Federal Reserve refinanced banks at the risk-free interest rate instead, bank profits would have been substantially lower before, but not after, the financial crisis.

References

Auer, R, G Cornelli and J Frost (2020), “Rise of the central bank digital currencies: Drivers, approaches and technologies”, BIS working paper 880. 

Brunnermeier, M K and D Niepelt (2019), “On the equivalence of private and public money”, Journal of Monetary Economics 106.

Kurlat, P (2019), “Deposit spreads and the welfare cost of inflation”, Journal of Monetary Economics 106.

Lucas, R E and J-P Nicolini (2015), “On the stability of money demand”, Journal of Monetary Economics 73.

McLeay, M, A Radia and R Thomas (2014), “Money creation in the modern economy”, Bank of England Quarterly Review, Q1.

Niepelt, D (2019), “Libra paves the way for central bank digital currency”, VoxEU.org, 12 September. 

Niepelt, D (2020a), “Digital money and Central Bank Digital Currency: An executive summary for policymakers”, VoxEU.org, 3 February. 

Niepelt, D (2020b), “Reserves for All? Central bank digital currency, deposits, and their (non)-equivalence”, International Journal of Central Banking 16(3).

Niepelt, D (2020c), “Monetary policy with reserves and CBDC: Optimality, equivalence, and politics”, CEPR Discussion Paper 15457.

Endnotes

1 See Auer et al. (2020) for an overview of CBDC projects. For a summary of pros and cons of CBDC and private sector alternatives, see Niepelt (2019, 2020a).

2 If the bank held reserves then its account at the central bank would be debited instead. The bank’s balance sheet would shorten but it would not suffer from a shortage of funds. 

3 In fact, under broad conditions, CBDC would not have any macroeconomic consequences (Brunnermeier and Niepelt 2019, Niepelt 2020b, 2020c). If deposits are not collateralised, ‘neutrality’ requires the central bank loan to be uncollateralised as well.

4 I use FRED data for the interest rate on reserves; Kurlat’s (2019) estimates of the risk-free, “illiquid” interest rate and the deposit rate; and FRED data as well as data constructed by Lucas and Nicolini (2015) for reserves and deposits. Following Lucas and Nicolini (2015) I use two alternative measures for the deposit series: The sum of checkable and savings deposits, or the sum of checkable deposits and money market deposit accounts.

5 Simplifying a bit, the formula for the equivalent gross loan interest rate reads:
Rl = Rr + (Rn-Rr) / (1-z) + c / (1-z).
Here, Rl, Rr, and Rn denote the gross interest rates on the central bank loan, reserves, and deposits, respectively. c and z denote the unit operating cost and reserves-to-deposits ratio, respectively.

6 The reserves-to-deposits ratio increases from a very low level (at which it had been since the early 1980s) to a maximum of 30% or 45%, depending on the deposit measure, in mid 2014. It reverts to 20% or 30% by the end of 2017.

- febbraio 08, 2021 Nessun commento:
Invia tramite emailPostalo sul blogCondividi su XCondividi su FacebookCondividi su Pinterest
Post più recenti Post più vecchi Home page
Iscriviti a: Post (Atom)

Post in evidenza

The Great Taking - The Movie

David Webb exposes the system Central Bankers have in place to take everything from everyone Webb takes us on a 50-year journey of how the C...

  • Slain bank CEO left no trail
    Nov. 5, 2010 Slain executive left no trail of financial irregularities, bank says BY CHRISTINA HALL FREE PRESS STAFF WRITER Th...
  • Central banks are secretly trading the markets
    Chris Powell: Gold market manipulation update Submitted by cpowell on Wed, 2015-10-28 21:55. Section: Documentation By Chris Powell, ...
  • Edwin Vieira's 'Pieces of Eight'
    James Turk reviews Edwin Vieira's 'Pieces of Eight' Submitted by cpowell on Sun, 2009-06-28 16:20. Section: Daily Dispatches 12:...

Cerca nel blog

Total visitors

Home

  • Home page

Archive

  • ▼  2026 (2)
    • ▼  agosto (1)
      • THE QUANTITATIVE BALANCING MANUAL
    • ►  febbraio (1)
  • ►  2025 (29)
    • ►  dicembre (2)
    • ►  luglio (4)
    • ►  marzo (1)
    • ►  febbraio (12)
    • ►  gennaio (10)
  • ►  2024 (20)
    • ►  dicembre (2)
    • ►  novembre (3)
    • ►  luglio (1)
    • ►  giugno (3)
    • ►  maggio (1)
    • ►  aprile (4)
    • ►  marzo (2)
    • ►  febbraio (3)
    • ►  gennaio (1)
  • ►  2023 (6)
    • ►  luglio (2)
    • ►  aprile (4)
  • ►  2021 (23)
    • ►  novembre (1)
    • ►  ottobre (4)
    • ►  settembre (1)
    • ►  luglio (1)
    • ►  giugno (2)
    • ►  maggio (1)
    • ►  aprile (1)
    • ►  marzo (2)
    • ►  febbraio (5)
    • ►  gennaio (5)
  • ►  2020 (106)
    • ►  dicembre (8)
    • ►  novembre (7)
    • ►  ottobre (8)
    • ►  settembre (10)
    • ►  agosto (5)
    • ►  luglio (4)
    • ►  giugno (12)
    • ►  maggio (11)
    • ►  aprile (11)
    • ►  marzo (18)
    • ►  febbraio (9)
    • ►  gennaio (3)
  • ►  2019 (61)
    • ►  dicembre (8)
    • ►  novembre (14)
    • ►  ottobre (2)
    • ►  settembre (10)
    • ►  agosto (7)
    • ►  luglio (3)
    • ►  giugno (2)
    • ►  maggio (2)
    • ►  marzo (7)
    • ►  febbraio (3)
    • ►  gennaio (3)
  • ►  2018 (66)
    • ►  dicembre (5)
    • ►  novembre (5)
    • ►  ottobre (7)
    • ►  settembre (9)
    • ►  agosto (7)
    • ►  luglio (5)
    • ►  giugno (8)
    • ►  maggio (8)
    • ►  aprile (6)
    • ►  marzo (2)
    • ►  febbraio (4)
  • ►  2017 (86)
    • ►  novembre (1)
    • ►  ottobre (2)
    • ►  settembre (3)
    • ►  agosto (8)
    • ►  luglio (14)
    • ►  giugno (1)
    • ►  maggio (4)
    • ►  aprile (5)
    • ►  marzo (17)
    • ►  febbraio (16)
    • ►  gennaio (15)
  • ►  2016 (378)
    • ►  dicembre (8)
    • ►  novembre (16)
    • ►  ottobre (34)
    • ►  settembre (38)
    • ►  agosto (31)
    • ►  luglio (34)
    • ►  giugno (35)
    • ►  maggio (55)
    • ►  aprile (43)
    • ►  marzo (19)
    • ►  febbraio (38)
    • ►  gennaio (27)
  • ►  2015 (222)
    • ►  dicembre (22)
    • ►  novembre (28)
    • ►  ottobre (31)
    • ►  settembre (25)
    • ►  agosto (20)
    • ►  luglio (14)
    • ►  giugno (15)
    • ►  maggio (20)
    • ►  aprile (19)
    • ►  marzo (7)
    • ►  febbraio (13)
    • ►  gennaio (8)
  • ►  2014 (377)
    • ►  dicembre (15)
    • ►  novembre (36)
    • ►  ottobre (37)
    • ►  settembre (25)
    • ►  agosto (16)
    • ►  luglio (27)
    • ►  giugno (52)
    • ►  maggio (30)
    • ►  aprile (39)
    • ►  marzo (39)
    • ►  febbraio (32)
    • ►  gennaio (29)
  • ►  2013 (318)
    • ►  dicembre (35)
    • ►  novembre (38)
    • ►  ottobre (42)
    • ►  settembre (18)
    • ►  agosto (16)
    • ►  luglio (28)
    • ►  giugno (33)
    • ►  maggio (26)
    • ►  aprile (13)
    • ►  marzo (21)
    • ►  febbraio (18)
    • ►  gennaio (30)
  • ►  2012 (686)
    • ►  dicembre (24)
    • ►  novembre (27)
    • ►  ottobre (39)
    • ►  settembre (53)
    • ►  agosto (60)
    • ►  luglio (55)
    • ►  giugno (22)
    • ►  maggio (81)
    • ►  aprile (38)
    • ►  marzo (89)
    • ►  febbraio (105)
    • ►  gennaio (93)
  • ►  2011 (1124)
    • ►  dicembre (57)
    • ►  novembre (111)
    • ►  ottobre (118)
    • ►  settembre (51)
    • ►  agosto (154)
    • ►  luglio (100)
    • ►  giugno (162)
    • ►  maggio (69)
    • ►  aprile (92)
    • ►  marzo (79)
    • ►  febbraio (82)
    • ►  gennaio (49)
  • ►  2010 (1793)
    • ►  dicembre (103)
    • ►  novembre (101)
    • ►  ottobre (70)
    • ►  settembre (67)
    • ►  agosto (83)
    • ►  luglio (179)
    • ►  giugno (172)
    • ►  maggio (188)
    • ►  aprile (257)
    • ►  marzo (216)
    • ►  febbraio (216)
    • ►  gennaio (141)
  • ►  2009 (2765)
    • ►  dicembre (60)
    • ►  novembre (129)
    • ►  ottobre (399)
    • ►  settembre (538)
    • ►  agosto (60)
    • ►  luglio (222)
    • ►  giugno (452)
    • ►  maggio (634)
    • ►  aprile (271)

Etichette

  • $1-per-watt mark
  • Abraham Lincoln
  • Abruzzo
  • abuse of power
  • accattonaggio
  • administering justice
  • Agenzia Milano Informazioni
  • AIG
  • American Monetary Act
  • American Monetary Institute
  • analista pentito
  • anarchism
  • Argentina
  • Austrian school
  • autogestione
  • Bailed Out Banks
  • Bailouts
  • Banca dei Lavoratori
  • Bank for International Settlements
  • Bank Loan
  • Bank Loans
  • Bank of England
  • Bank of England Nominees Limited
  • Bank of England Nominees Ltd
  • bankers fear
  • Banking
  • Banking law
  • Bankistan
  • banks
  • Belgium
  • Berkshares
  • Big Banks
  • Big Zanza Banks
  • biggest real estate bankruptcy
  • Bilderberg
  • BIS
  • Black
  • black list
  • Bloomberg
  • Board of Governors of the Federal Reserve System
  • BOEN
  • bretton woods
  • Bretton Woods Project
  • British Empire
  • Bush
  • Campaign for Liberty
  • capitalismo italiano
  • carbon mitigation
  • CDS
  • central banks
  • cheating
  • Chernobyl
  • China
  • CIA
  • Cina
  • class action
  • class warfare
  • CLEARSTREAM
  • cleptocrazia
  • Cold fusion
  • COMEX
  • Community Currency Magazine
  • complementary currencies
  • Congressional Research Service
  • cooked books
  • Corporate tactics
  • corruption
  • Court Admissions
  • criminal enterprise
  • Cristiano Lovatelli
  • currency debasement
  • D.C. Circuit
  • debt money.
  • deceptive accounting
  • Democrats
  • Dennis Kucinich
  • Depleted Uranium
  • Derechos Especiales de Giro
  • derivatives
  • DHS
  • DISGRUNTLED MILITARY VETERANS
  • dollar
  • drugs
  • East India Company
  • Economic hit man
  • EHM
  • El Economista de Cuba
  • ESO
  • ETF
  • Eugenio Cefis
  • European Settlements Office
  • exchange
  • Ezra Pound
  • failed bank
  • Federal Reserve
  • Federal Reserve System
  • Field Manual
  • finance minister
  • financial barons
  • financial disaster
  • financial houses
  • Financial Stability Forum
  • financial terrorism
  • financiers
  • financing
  • First Bank of Idaho
  • Florida
  • FOIA
  • fondi europei
  • Founding fathers
  • Francesco Pazienza
  • fraud
  • Freedom of Information Act
  • FSF
  • gambling
  • GATA
  • Geithner
  • General Growth Properties Inc
  • genuine consent
  • Gerald Celente
  • GGP.N
  • Giacinto Auriti
  • Giorgio Steimetz
  • Giuliani
  • global financial crisis
  • gold
  • Goldman Sachs
  • Green New Deal
  • greenback
  • Group of 20
  • Henderson
  • Hitler
  • IFI
  • Il fantasma della povertà
  • IMF
  • Income Tax
  • information broker
  • intelligence
  • interessi
  • interest
  • IRS
  • Israel
  • Ithaca Hours
  • Joseph Stiglitz
  • JP Morgan
  • Justice Department
  • Labour Treasury Certificates
  • ladri
  • Latin America
  • lawsuit
  • lay off
  • LBMA
  • legal tender
  • legge Marcora
  • Lending
  • LETS
  • Lincoln
  • local currency
  • Logan Act
  • low-carbon lifestyles
  • Luttwak
  • Manipulations
  • marco saba
  • market manipulation
  • Mayer Brown
  • Milena Gabanelli
  • ministeri
  • Modelli di controllo
  • Mogambo Guru
  • monetary policy
  • monete locali
  • money
  • moneyboarding
  • moral hazard
  • Mortgage Fraud
  • MOVIMIENTO POR LA SEGUNDA REPUBLICA ARGENTINA
  • Naked short
  • national security
  • negazionismo
  • new American Revolution
  • New School for Social Research
  • New World Order
  • NEXUS
  • Obama
  • Obama administration
  • occupazione delle fabbriche
  • odious debts
  • olaf
  • olocausto economico
  • OMO
  • Open Market Operations
  • PA acefala
  • padroni in fuga col bottino
  • Pajamas TV
  • palliativi econiomici
  • patacones
  • Paul Glover
  • Pedro Solbes
  • Pepe Escobar
  • photovoltaic
  • Pierluigi Paoletti
  • pirates
  • Plunge Protection Team
  • povertà terminale
  • power plant
  • PPT
  • privatization
  • protest
  • Protezione Civile
  • Quantitative Balancing
  • RAN
  • real estate fraud
  • regioni
  • revolution
  • rigged currency
  • rigged gold
  • Rightwing Extremism
  • robber barons
  • Ron Paul
  • Sarbanes-Oxley
  • SCEC
  • SEAL
  • Secrecy
  • secret
  • secret clearing
  • secret legal memos
  • seigniorage
  • shoà economica
  • sick man of Europe
  • signoraggio
  • silver
  • sindacati
  • social-economic academy
  • sovereignty
  • sovereignty movements
  • Spain
  • stimulus
  • subpoenas
  • sustainable consumption
  • Sustainable Economies
  • swindles
  • Switzerland
  • TARP
  • Tax Day
  • taxed to death
  • Tea Parties
  • Tea Party
  • terremoto
  • Testamento economico
  • torture
  • tradimento
  • Treasury Department
  • Tremonti
  • Trends Journal
  • Trends Research Institute
  • trial by jury
  • Troubled Asset Relief Program
  • Tucson
  • U.S. Army
  • U.S. Treasury
  • UBS
  • Unione internazionale del Notariato
  • usura
  • V come Vendetta
  • Wall Street
  • war in Bankistan
  • warfare
  • Warren Buffer
  • Washington
  • waterboarding
  • White House
  • Worker Exploitation
  • world bank
  • World leaders
  • World War II
  • Yuan
  • Zapatero

Segnala una violazione

Our campaign

More blogs to follow:

  • LewRockwell
    Punching The Panda: US Deploys New Missile System Near China - Watch today’s Liberty Report here. The post Punching The Panda: US Deploys New Missile System Near China appeared first on LewRockwell.
    15 ore fa
  • WEB OF DEBT BLOG
    Dollar Reset 2.0: Stablecoins, Treasury Bills and the Case for Public Banks - The Digital Dollar Drain, image by ScheerPost Washington’s stablecoin strategy could shore up the dollar by making U.S. Treasury bills the backing for a ne...
    17 ore fa
  • oftwominds-Charles Hugh Smith
    What's the Point of AI, Anyway? - *The point of AI is profit, dependence and dominance cloaked with Happy Story Hoopla about super-abundance. We have a super-abundance already--of malicious...
    2 settimane fa
  • Simon Thorpe's Ideas
    IOUNet - an update - IOUNet is an idea that I have been working on since 2014 when I first posted about the potential for an exchange system that doesn't need money. Earlier t...
    3 settimane fa
  • Rendita monetaria e democrazia
    Perché diciamo NO al "Partito Nazionale Sfascista" - Il manifesto del "Partito Sfascista" pubblicato sul blog descrive una strategia basata sull'applicazione iper-zelante, letterale e rigida di qualsiasi n...
    1 mese fa
  • Wanta Revelations
    Bedsores In Sandy Springs Nursing Homes: A Sign Of Neglect And Legal Liability - Key Takeaways Bedsores, also known as pressure ulcers, are a serious and all-too-common issue for elderly residents in nursing homes. The presence of bedso...
    3 mesi fa
  • Le Banquier Garou
    Se moquer du peuple suisse à propos du seigneuriage... - Comment les Suisses ont été trompés sur le seigneuriage Le seigneuriage, c'est-à-dire les bénéfices tirés de l'émission monétaire, a toujours constitué ...
    1 anno fa
  • Rowans-blog
    Spuddling the facts, muddying the waters. - In his very cleverly worded piece in the Sunday Times of 18.8.19, entitled "...It casts itself as the good guy, but the EU's aim has been to humiliate an...
    7 anni fa
  • Blog - Public Banking Institute
    Pennsylvania's public banking movement draws the support of the Black Business Review and key cities - [image: Pittsburgh, PA] *Pittsburgh, PA. Photo by Igor Oliyarnik.* Black Business Review’s Marilyn Kai Jewett writes favorably of Pennsylvania’s publi...
    7 anni fa
  • Affaire Clearstream "Saison 3".
    Today, special Iceland accounts for blog readers - Today, Clearstream Luxembourg accounts "Special Iceland" Clearstream 2001 - Kaupthing Bank On 9 October 2008, following a major banking and fina...
    11 anni fa

Author's Page on Facebook

Buy my book:

Encyclopedia of Chess Gambits

La causa AUDIT THE ECB

RSS: Iscriviti alle news

Post
Atom
Post
Tutti i commenti
Atom
Tutti i commenti

Lettori fissi

Powered By Blogger

Misteri e magie dietro alla moneta...

Misteri e magie dietro alla moneta...
Scarica "Moneta Nostra"

Link consigliati:

  • Fronte di Liberazione Nazionale
  • Blog di Scacchi e Gambetti
  • Blog Le Banquier Garou
  • Centro Studi Monetari
  • Blog su uranio e radiocontaminazione
  • Il blog di ALBAMED
  • Il sito dell'autore del Blog
Tema Viaggi. Powered by Blogger.